Parameter estimation is the craft of extracting the best values for a model's adjustable constants from noisy, incomplete observations. In physics, every theory has free parameters — the mass of a neutron star, the stiffness of a crystal lattice, the coupling strength between particles — and the data rarely pins them down exactly. The challenge is to find not just a good fit, but a defensible one: how well is each parameter constrained, and which values are ruled out? This discipline sits at the heart of experimental science, turning raw measurements into quantitative claims about the world.
History
The method of least squares was introduced by Legendre and Gauss in the early 1800s for astronomical orbit fitting, and the likelihood principle was formalized by Fisher in the 1920s. Bayesian parameter estimation has roots in Bayes' theorem (1763) but became computationally practical only in the late 20th century.
How it works
The standard approach is to define a likelihood function that scores how probable the observed data is for a given set of parameter values. The best parameters maximize this score, and the curvature of the score near the peak gives error bars. Modern methods add Bayesian priors to encode prior knowledge, and Markov Chain Monte Carlo (MCMC) algorithms to explore high-dimensional parameter spaces when the model is complex. The key is to propagate uncertainties honestly, so that conclusions come with honest confidence intervals.
In practice
Used everywhere from gravitational wave astronomy (estimating black hole masses and spins from detector signals) to plasma physics (inferring turbulence parameters from diagnostics) and medical imaging (reconstructing tissue properties from sparse scans).
Fun fact
The first major use of least squares was to predict the orbit of the newly discovered dwarf planet Ceres in 1801, after it was lost behind the Sun — Gauss's fit let astronomers find it again exactly where predicted.
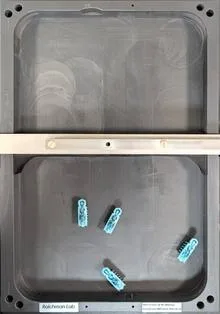
A piston in a cylinder with gas usually moves when the gas pushes on it. But there is a piston that moves when the space in front of it is empty. Every five seconds, it checks the space near its wall, and if no one is there, it takes a step inward, compressing the gas without direct mechanical force.
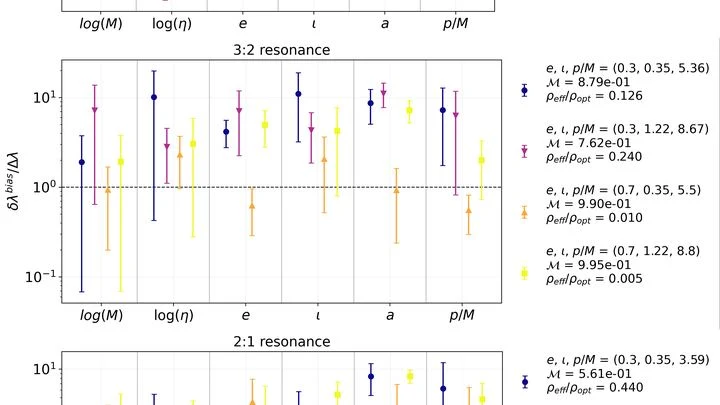
Imagine a simultaneous interpreter in a room where two people are speaking: they must keep up with both meaning and intonation, but if the speech is too fast, only a paraphrase remains. That's roughly how scientists feel as the stream of gravitational waves from black hole and neutron star mergers grows, while precise signal calculations lag behind.
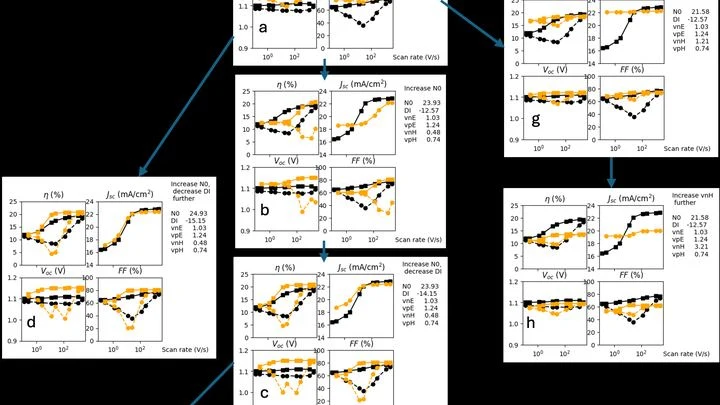
A perovskite solar cell is like a young athlete: it performs brilliantly at first, but tires with age. Over eight hours, its performance drops noticeably, with no visible cause like cracks or dust. Scientists took one cell and recorded its performance at 0, 90, 280, and 480 minutes of its life.
If a smell seeps into a room through a slightly open door, you could stand in the middle and sniff. But the most accurate way to catch the moment the smell arrives is to stand right at the threshold. A cell behaves much the same way when it needs to measure the concentration of a substance around it.
If you accelerate an observer to near-light speed, the emptiness around them stops being cold. A thermal glow emerges — an effect predicted in 1976 and named after William Unruh. For earthly accelerations, this glow is vanishingly faint, like a whisper at a rock concert.
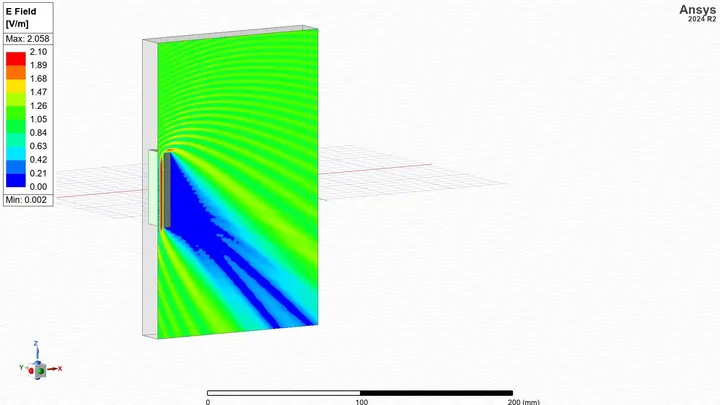
When a radio wave encounters a building in its path, it doesn't just reflect or get absorbed: it bends around it, much like ocean waves flowing around a rock, leaving calm water behind. In radiophysics, this phenomenon creates a radio shadow — a complex pattern of zones where the signal is amplified or attenuated, which scientists call a radio portrait.
Hybrid perovskites are the rising stars of photovoltaics: their efficiency is growing so fast it feels like we're on the brink of a solar revolution. But these materials, like intricate atomic mosaics, are extremely vulnerable — moisture, heat, and light quickly turn them to dust.
Eight hundred participants, firms and workers, enter the market. Each holds a strict preference list in mind. The challenge: pair up so that no one wants a do-over. In mathematics, this is called a game theory with a ban on repeat alliances, and its roots trace back to the work of John von Neumann and Oskar Morgenstern.
A spectrum is like a photograph of a material's inner workings, taken with light. When a beam passes through or reflects off a sample, molecules leave characteristic dark bands, peaks, on that photograph. But if the image is overexposed or veiled in gray, making out details becomes nearly impossible.
The outer crust of a neutron star is like a layered cake, where each layer is a strictly defined filling. It's a crystalline lattice of atomic nuclei immersed in a sea of electrons. The deeper you go, the stronger the pressure, and the heavier the nuclei that can exist there without falling apart.
A figure skater glides across the ice, gradually moving toward the center. Their trajectory isn't a perfect spiral: sometimes they catch the rhythm of the music and add an extra turn, slightly changing their speed. That's roughly how a small black hole behaves when it falls into a supermassive one.
A doctor holds a stack of test results taken at different times. Each sheet on its own is just a snapshot of a single day, but what you want is a whole movie of how the disease unfolded. A neural network called Tempo learns to glue these scattered frames into a smooth reel.
When a person breathes, air doesn't flow in a steady stream but in waves. Previously, doctors and scientists only looked at overall numbers: how much air entered per breath, what the peak flow was. But within a single breath, there are nuances — small variations that speak to the workings of nerves and muscles. The new approach breaks a breath into parts, much like a musician breaks a chord into individual notes.
When a neutron or proton enters an atomic nucleus, it behaves like a ball hitting a rough wall: it can bounce off in different ways, depending on where it hits.
Thousands of models simmer in a single cauldron, and the steam rises thick and impenetrable. Each whispers something about the future of El Niño, but in the general din you cannot tell who is right and who is just boiling over.
When a top quark is born in a particle detector, it immediately decays into a shower of other particles. Catching a hint of new physics in that shower is like hearing a whisper at a rock concert. You need not just a good microphone, but the ability to subtract the roar of the amplifiers and the hum of the crowd.
A neutron star is a sphere the size of a city, but it weighs as much as one and a half Suns. Inside such a sphere, matter is so compressed that a teaspoon of it would weigh billions of tons. But physicists don't fully know what this matter is made of.
Inside a neutron star, matter is compressed to unimaginable densities. Previously, scientists speculated about its exact makeup, cycling through possible equations linking pressure and density. The new method tosses out guesswork: it directly ties the measurable mass and radius to the internal structure.
In a tropical forest, the dry season gives way to the rainy season, and with the weather, the rules of life change: some animals go into hibernation, while others come out of hiding. Likewise, in complex systems, from climate to economics, the links between processes are not set in stone. They depend on a hidden "regime" that itself switches from time to time.
On an old film strip of rainfall, only the brightest frames are visible, and between them lies noise. A meteorologist assessing flood risk long looked only at such frames, that is, at annual rainfall maxima. Everything else, thousands of daily observations, remained off-screen. The new method develops the entire film, and details that were previously invisible come into view.